If We Only Count the Jobs Inside the Data Center, We're Measuring the Wrong Thing
Looking beyond the property line to understand the economic impact of America's data center buildout
In the first article in this series, I made the case that the data center is bigger than the building. What looks like a technology asset from the outside actually sits at the center of a much larger industrial ecosystem involving power, manufacturing, engineering, construction and supply chains.
That changes how I think about another question that follows almost every major data center announcement: How many permanent jobs will it create?
It's a fair question. Communities should understand what they are receiving in return for the infrastructure, resources and incentives these projects may require. But the question becomes incomplete when the analysis stops at the property line.
I grew up in the Rust Belt and spent roughly two decades of my career in manufacturing. That experience taught me that the economic impact of an industrial facility isn't limited to the people who walk through its doors every morning.
If we only count the jobs inside the data center, we're measuring the wrong thing.
I've Seen What Happens When the Ripple Moves the Other Way
Early in my career, I worked for Modine Manufacturing and Donaldson Company, and later at Kohler's manufacturing facility in Searcy, Arkansas. Those experiences exposed me to manufacturing operations in smaller American communities throughout the Midwest and South.
Over the years, I watched that landscape change. Plants closed. Operations consolidated. Production moved. There were business reasons behind many of those decisions, and having spent much of my career responsible for cost, productivity and competitiveness, I understand the pressures that drove them.
But a factory's footprint extends well beyond its gates. It buys materials, components, equipment and services. It relies on suppliers, contractors and transportation, and those businesses employ people and have suppliers of their own.
When industrial activity leaves a community, more disappears than the jobs inside the factory.
Economic research has documented that effect more broadly, including persistent impacts on employment, labor force participation and income in communities heavily exposed to manufacturing job losses. That's part of why I look at today's infrastructure investment cycle differently.
Today, we may be watching enormous new demand for power and infrastructure begin moving in the opposite direction.
Follow the Economic Ripple
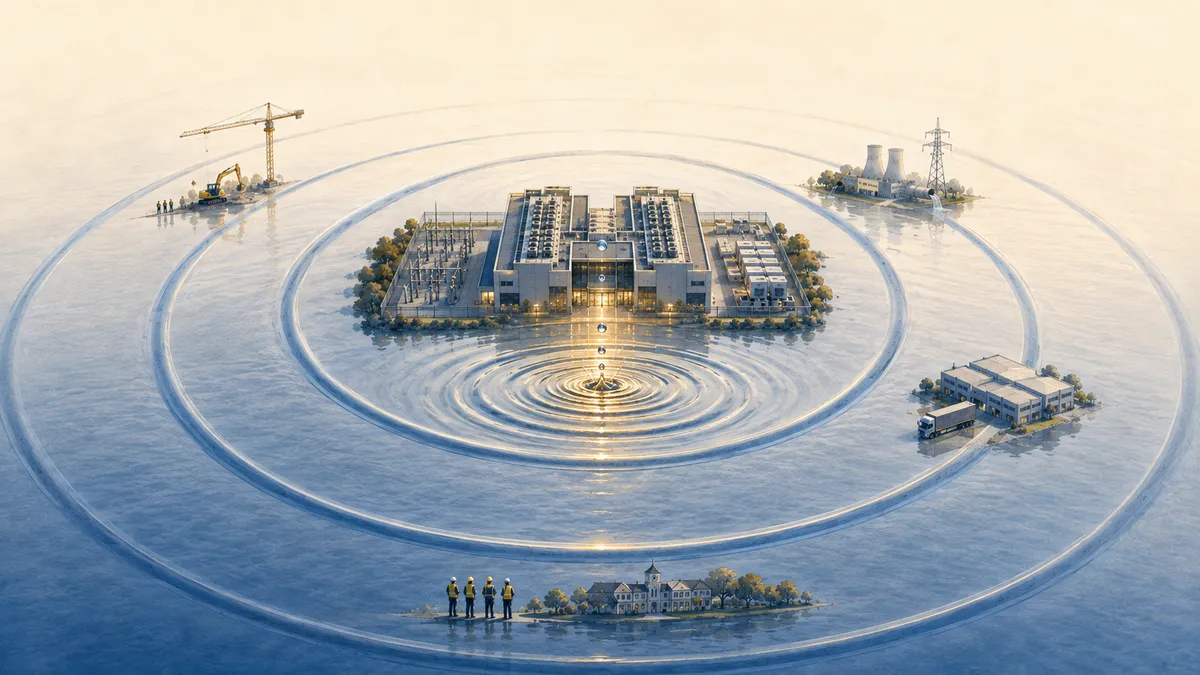
Think about dropping a stone into still water. The point where it hits is obvious, but the impact doesn't stay there. The ripples move outward, each reaching farther from the original point.
The data center is the center of the ripple, not the boundary of its economic impact.
At the center is the data center investment itself. The first ripple reaches the companies developing, engineering, powering, cooling and constructing it. The next reaches manufacturers producing transformers, switchgear, generators, cooling systems and other critical equipment.
Those manufacturers need steel, copper, aluminum, engines, electronics, controls, fabricated components and manufacturing equipment. Their suppliers have suppliers of their own. And the ripple isn't limited to equipment that ultimately goes inside the data center. Building the facilities, power generation, substations, transmission infrastructure and other supporting assets creates demand for cranes, earthmoving equipment, concrete equipment, trucks, tools and the construction supply chain behind them.
The ripple keeps moving through transportation, logistics, contractors, skilled trades and services, reaching communities that may be hundreds or thousands of miles from the data center that created the original demand.
If we only measure what happens at the center of the ripple, we're missing much of the economic story.
The Ripple Is Already Moving
We can already see evidence of this in manufacturing investments across the country. Eaton has announced a $340 million South Carolina transformer facility expected to create roughly 700 jobs. Siemens has invested more than $165 million to expand electrical manufacturing across the Carolinas, adding about 350 jobs to support fast-growing AI and data center markets. GE Vernova announced nearly $600 million of investment across U.S. factories and facilities, with plans to create more than 1,500 factory and engineering jobs.
Generac helps show what happens beyond the first ripple. The company is investing $250 million to equip multiple factories to make larger generators for data centers and expects to add about 1,000 workers. More generator production also means more demand for engines, alternators, electronics and controls, and behind those components are steel, copper, aluminum, fabrication and still more suppliers.
That's the ripple.
PwC, in an analysis commissioned by the Data Center Coalition, estimated that the U.S. data center industry supported 5.5 million jobs, contributed $926.9 billion to U.S. GDP and generated $204.4 billion in federal, state and local taxes in 2024.
Those numbers deserve appropriate scrutiny because the study was industry sponsored. But we don't have to rely solely on an economic model to see the pattern. Companies are investing real capital, expanding real factories and hiring real people to respond to demand moving through the infrastructure ecosystem.
This Isn't Manufacturing for Manufacturing's Sake
I'm not arguing that we should manufacture more products in America simply because manufacturing is inherently good, nor that every plant closure or production move I witnessed earlier in my career was a mistake.
I've spent too much of my career responsible for cost, quality, productivity and competitiveness to believe that.
The United States remains one of the world's most productive major economies, but American manufacturers still compete for customers, people and capital in a global market. If this infrastructure cycle creates an opportunity to expand our domestic manufacturing base, that capacity has to be competitive.
It has to produce quality products at the right cost and at the pace customers require. Capital has to be deployed intelligently. Productivity has to improve. Ultimately, the investment has to create value.
Demand is an opportunity, not a guarantee.
And the same economic ripple creating that opportunity also creates pressure.
When Opportunity Creates Pressure
Imagine you're leading a successful manufacturer and demand suddenly accelerates. Your backlog grows. Customers want shorter lead times. The immediate answer might appear obvious: add people, equipment, shifts or square footage.
But anyone who has scaled an operation knows it isn't that simple.
Can your suppliers support the additional volume? Can engineering keep pace? Do you have the right people? Can your managers effectively lead a larger organization? Can your planning and scheduling systems manage the increased complexity? Can working capital support the growth? Can you maintain safety, quality, cost and delivery while everything around you is moving faster?
And perhaps most importantly, can you increase capacity without allowing the cost of complexity to consume the value of the growth?
Growth that isn't accompanied by productivity can create revenue without creating value.
That's the challenge I think gets overlooked when we talk about the manufacturing opportunity surrounding the data center buildout. The opportunity may be substantial, but capturing it profitably requires much more than adding capacity.
For small and midsize manufacturers and infrastructure companies participating in this buildout, that may become one of the defining operating challenges of the next several years.
Measure the Whole Equation
None of this means every proposed data center is automatically good for every community. Questions about electricity demand, generation and transmission investment, water use, incentives, utility rates and local economic benefit are legitimate.
Measure the costs. Measure the benefits. But measure all of them.
If we evaluate the economic impact of a data center primarily by counting the people working inside it, we miss the manufacturers adding capacity, the suppliers receiving orders, the contractors doing the work and the communities where those businesses and employees are located.
The data center is where the stone hits the water. The economic story is in the ripples.
Is Your Organization Prepared to Capture the Opportunity?
For CEOs, that economic ripple creates another question.
If the opportunity in front of your company accelerated tomorrow, is your organization actually prepared to capture it profitably?
A growing backlog can look like success. A new customer can look like success. A factory expansion can look like success. But each puts additional pressure on leadership, people, processes, capacity and the systems required to execute consistently.
That's why I've developed the 6P Execution Diagnostic™, a five-minute assessment that gives CEOs a quick view of their organization's ability to execute and scale across six dimensions: Plan, Performance, People, Process, Pace and Perpetuate.
https://www.operatorsview.com/assessment
You'll receive an overall execution score and a view of where your organization appears strongest and where friction or constraints may be developing. It isn't intended to diagnose your business in five minutes. It's designed to help you identify where growth may be putting pressure on the organization and what deserves a closer look.
Take five minutes and ask yourself: Is the organization behind my business prepared for the opportunity in front of it?
If the results confirm that you're well positioned, that's useful information. If they expose a constraint that could make profitable growth harder to achieve, the results give us a better starting point for a focused conversation about why it's happening and what the next step might look like.
Because ultimately, demand alone won't determine which companies benefit most from this infrastructure cycle.
The companies that win won't simply be the ones with demand. They'll be the ones capable of executing against it.
That's where I'll go next in this series.